By CPA Stephen Kimani, Optima Accounting Services · Last updated 18 November 2026
"We're a non-profit, so eTIMS doesn't apply to us." We hear this often from NGOs, churches, clubs and foundations, and it is only partly true. Donor grants do not need eTIMS invoices. But many non-profits earn some income from activities, pay suppliers, and employ staff. Under KRA's 2026 data-matching regime, each of those can create tax exposure.
This guide sets out where eTIMS applies to a non-profit, where it doesn't, and what to put in place.
Start with your tax exemption, not eTIMS
A non-profit's income is exempt from income tax only if it qualifies under paragraph 10 of the First Schedule to the Income Tax Act. The Income Tax (Charitable Organisations and Donations Exemption) Rules 2024 set out the process. In outline, the organisation must:
- Be registered under the relevant law (NGO, PBO, Societies or Trustees Act)
- Have a governing document that limits its objects to charitable purposes and prohibits private benefit
- Spend its income in Kenya, or for purposes that benefit residents of Kenya
- Hold a valid exemption from the Commissioner
Business income is exempt only in narrow cases. It must be applied solely to charitable purposes, and earned while carrying out those purposes or from work mainly done by beneficiaries.
Why this matters for eTIMS: if your exemption has lapsed, or does not cover an income stream, your surplus may be taxable at the corporate rate. Then every expense without a valid eTIMS invoice may be disallowed, and that increases the tax.
Where eTIMS applies to a non-profit
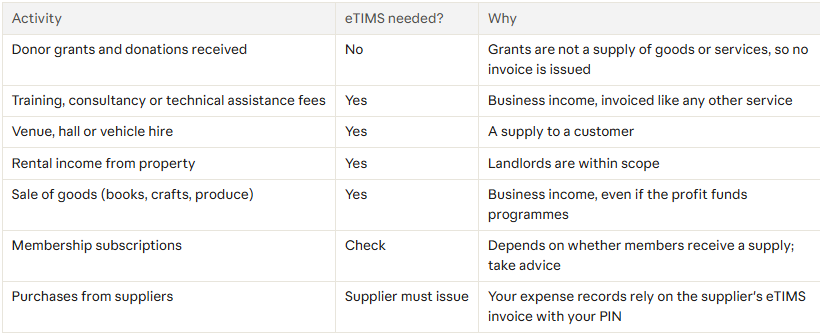
The 2024 Regulations extend electronic invoicing to anyone carrying on business, whether VAT-registered or not. A non-profit with income-generating activities therefore usually needs eTIMS, typically eTIMS Lite or the Online Portal.
The spending side: donors are asking too
Even a fully exempt organisation has reasons to insist on eTIMS invoices from suppliers.
- Donor audits: auditors increasingly test whether expenditure is backed by compliant tax invoices. An eTIMS invoice is strong, independent proof that a purchase happened.
- Fraud control: an eTIMS invoice ties a payment to a registered supplier PIN, which makes fictitious suppliers and inflated invoices harder.
- Taxable activities: if part of your income is taxable, expenses linked to it need eTIMS support to be deductible.
Field suppliers and community programmes
Programme work in counties often relies on small suppliers: local transporters, caterers, farmers and artisans. Many cannot issue eTIMS invoices.
The solution is buyer-initiated invoicing. Your finance team raises the invoice in eTIMS on the supplier's behalf, and the supplier accepts it. Build this into field procurement procedures, and train project officers, not only finance staff.
Your other obligations as an employer
NGOs and churches with staff are employers like any other. eTIMS does not cover salaries, which fall under PAYE, but you must still:
- Deduct and remit PAYE, SHIF, NSSF and the Affordable Housing Levy every month
- Apply the correct treatment to allowances, per diems and benefits
- Account for withholding tax where you make payments that attract it, such as some professional and consultancy fees
See our 2026 Kenya payroll deductions guide for current rates.
A 2026 compliance checklist for non-profits
- Confirm your income tax exemption is valid and covers each income stream
- List every income-generating activity and confirm each is invoiced through eTIMS
- Onboard on eTIMS Lite or the Online Portal if you have any business income
- Require eTIMS invoices with your PIN in all supplier contracts and grant procurement rules
- Set up buyer-initiated invoicing for field suppliers
- Reconcile eTIMS data with your ledger monthly, by grant or project code
- File annual income tax returns, even where income is exempt
Frequently asked questions
Do we issue an eTIMS invoice to a donor? No. Grants and donations are not taxable supplies, so you do not invoice the donor through eTIMS.
We're tax-exempt. Do we still file returns? Yes. Exemption reduces the tax due; it does not remove the obligation to file, and KRA validates returns against its data.
Can a church be required to use eTIMS? A church's offerings and tithes are donations. If the church also earns business income, such as hall hire, a school or a bookshop, that income is invoiced through eTIMS.
How Optima Accounting can help...
Optima Accounting and Advisory is a reputable accounting firm in Nairobi. We supports NGOs, churches and clubs with grant accounting, donor reporting and tax compliance, for organisations in Kenya. Book a free NGO compliance review and we will check your exemption, eTIMS set-up and internal controls to mitigate against tax risks emanating from the 2026 eTims rules.
Have a question about this?
Our accountants can look at your specific situation.